IN Brief:
- The September WOW Supply Chain Activity Index, covering August data, rose 7.2 points to 43.7.
- WOW’s dry-van Deployment Ratio climbed from 0.75 to 1.18 and contributed six points of the monthly increase.
- The index remains below its neutral level of 50, while warehouse utilisation weakened despite stronger temporary trailer demand.
Warehouse on Wheels has reported its strongest US Supply Chain Activity Index reading in more than three years, with August data lifting the composite to 43.7 as customers increased their use of short-term trailer capacity ahead of the fourth-quarter peak period.
The September edition of the index rose 7.2 points from July’s 36.4 reading. It is the highest result since February 2023 and sits 10.3 points above the January 2026 low of 33.4, although Warehouse on Wheels still classifies the current level as contraction rather than expansion.
The largest movement came from the company’s own dry-van fleet. Its Deployment Ratio increased from 0.75 in July to 1.18 in August, meaning more trailers began rental periods than were returned for the first time since March.
That change accounted for six of the index’s 7.2-point monthly increase. The eight external freight, manufacturing, warehouse, and industrial indicators making up the rest of the composite added only around 1.2 points between them, leaving the rebound heavily influenced by the proprietary trailer measure.
The Deployment Ratio compares dry vans beginning rentals with those coming off rent. A reading below one indicates that more trailers are being returned than deployed, while a figure above one means customers are adding temporary trailer capacity on a net basis.
The move above one therefore suggests businesses became more willing to add flexible storage during August. It does not necessarily indicate the same confidence in conventional warehouse expansion, because a trailer can be positioned for a short period and returned once seasonal or temporary demand subsides.
That distinction is reinforced by the wider data. The Cass Freight Index shipments component improved during the month and transportation pricing strengthened, but warehouse utilisation in the Logistics Managers’ Index fell from 66.1 to 59.6. The ISM manufacturing measure also eased.
Temporary trailer demand and weaker warehouse utilisation can coexist. A company may need short-term space for seasonal inventory, packaging, returns, production overflow, or inbound goods waiting for a later outbound window without being prepared to commit to another building or a long lease.
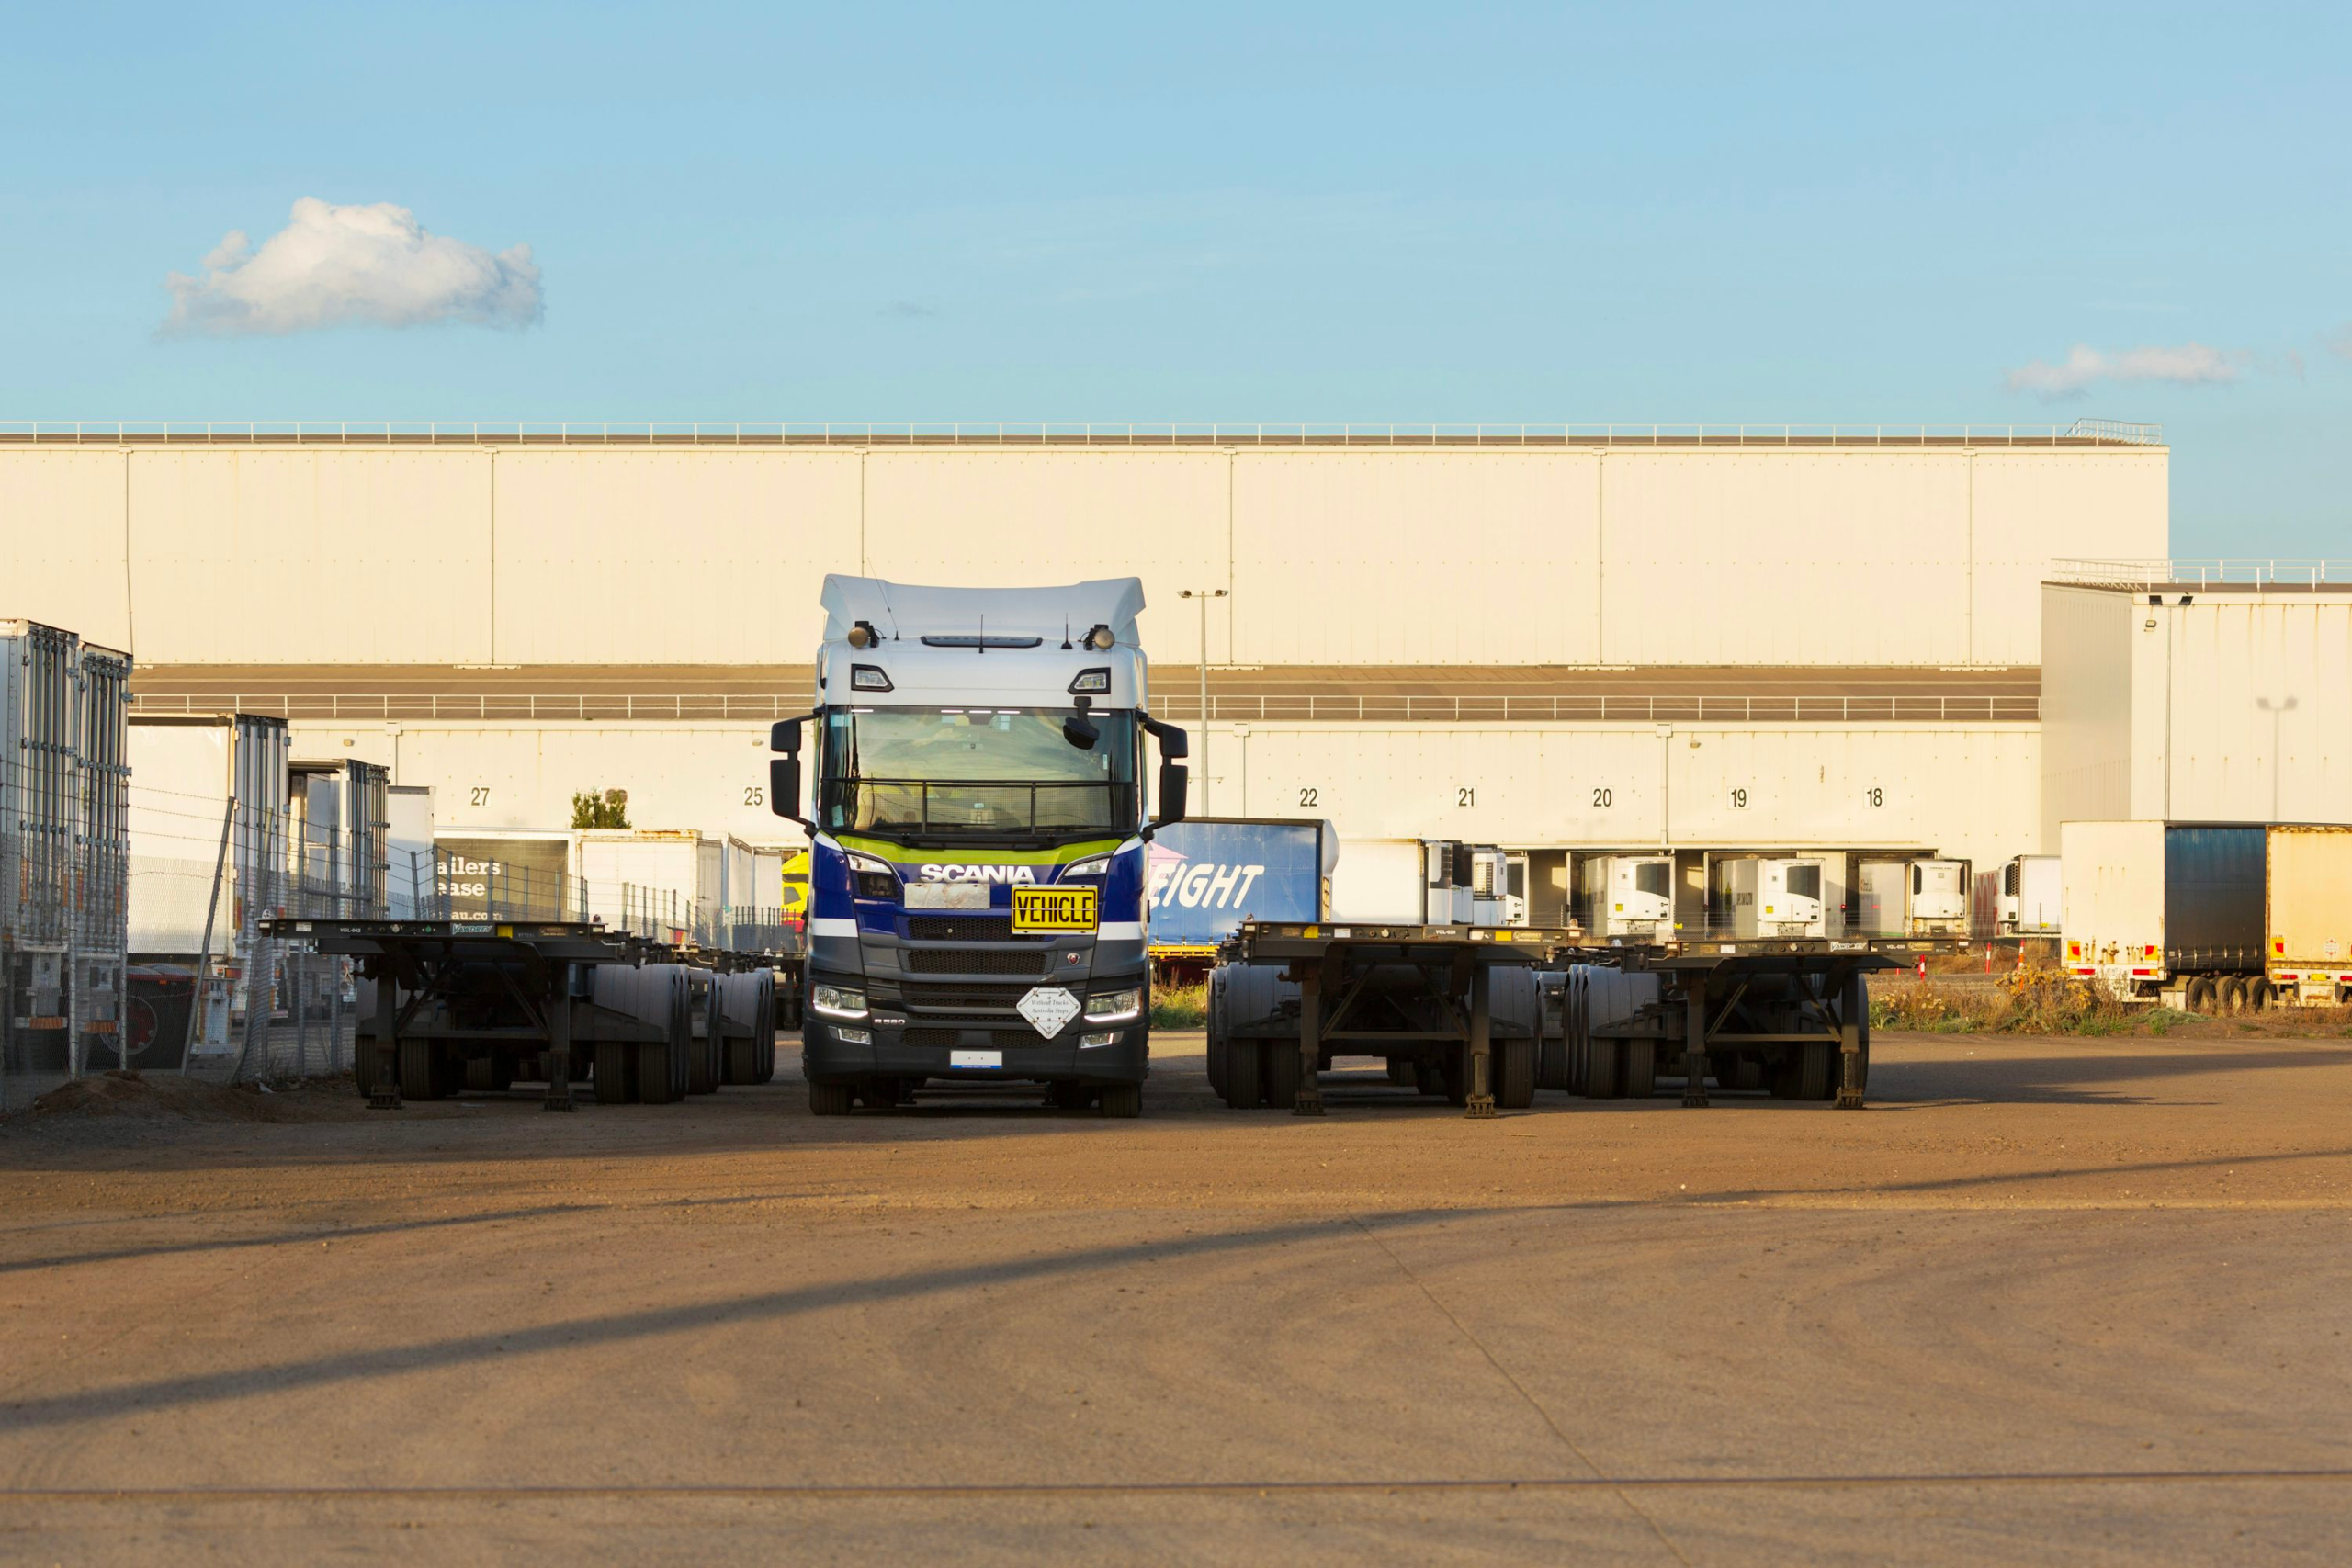
A storage trailer turns existing yard space into flexible capacity. It can be positioned near a loading door, filled with goods that do not require frequent picking, and removed when the peak passes. For some operations that is faster and less disruptive than finding, fitting out, and staffing external overflow warehousing.
The trade-off is functionality. A trailer provides cubic capacity but not the full operating environment of a warehouse. It does not offer the same access, racking, picking efficiency, labour environment, or inventory handling capability, so it becomes less suitable as storage duration and handling frequency increase.
The previous WOW reading had dropped to 36.4, reversing much of the improvement seen earlier in the year and leaving the index close to its January low. August therefore represents a sharp change from the previous month rather than confirmation of an established recovery.
The index runs from zero to 100, with 50 treated as the long-run neutral point. Warehouse on Wheels places readings from 30 to 45 within its contraction band, so 43.7 is considerably stronger than July but remains short of neutral.
Across the first eight months of 2026, the index has averaged 39.6. The August result is materially above that level, although the company has cautioned against treating one month as proof that freight and logistics demand has entered a sustained upswing.
John Brooks, CEO of Warehouse on Wheels, said the company’s trailer data appeared to be moving before several broader indicators. He also emphasised that another month would be needed to show whether the shift represented a genuine change in direction rather than a temporary preparation cycle.
The timing makes the distinction particularly important. September and October are periods when retailers, distributors, and consumer goods companies often position inventory for year-end demand. Goods may arrive weeks before final customer orders, creating temporary pressure around docks, yards, and warehouse space even if underlying annual demand remains subdued.
Manufacturers can face similar pressure where finished goods accumulate ahead of scheduled customer deliveries or incoming raw materials arrive faster than production consumes them. A temporary trailer can absorb some of that imbalance without forcing the business into a longer property commitment.
The same flexibility appeals to 3PLs managing customers with uncertain forecasts. They can add storage incrementally rather than securing permanent space for a peak that may last only several weeks, although yard capacity, security, weather exposure, and trailer access still have to be managed.
The rebound therefore says as much about the type of capacity companies want as the amount. Businesses appear more willing to add space than they were in July, but the strongest signal comes from an asset designed to be returned easily if demand weakens.
That makes the next monthly reading important. Another result around the low-to-mid 40s would suggest the increase in flexible capacity is persisting, while a fall back towards the high 30s would make August look more like a seasonal spike.
Warehouse operators and 3PLs have to make longer-term decisions before that evidence is complete. Labour, buildings, transport equipment, and automation cannot always be added at short notice, but committing too aggressively to permanent capacity against a temporary rebound creates its own cost.
The index also needs to be interpreted with its methodology in mind. Warehouse on Wheels’ proprietary trailer measure gives the company an early view of flexible storage demand, but it can exert a substantial influence on the composite when deployment changes sharply.
August demonstrates that clearly. Six of the 7.2 points came from trailer deployment while warehouse utilisation weakened. The US logistics market is showing greater willingness to add capacity, but much of that demand is still choosing equipment that can be handed back once the peak has passed.