IN Brief:
- ICIS assessments show chemical and palm oil freight rising across most intra-Asia lanes in the two weeks to 28 October.
- Palm oil shipping from Southeast Asia to India and China reached its highest assessed levels in more than three years.
- Congestion, competing tanker employment, and higher bunker costs are limiting prompt shipping options despite new vessel deliveries.
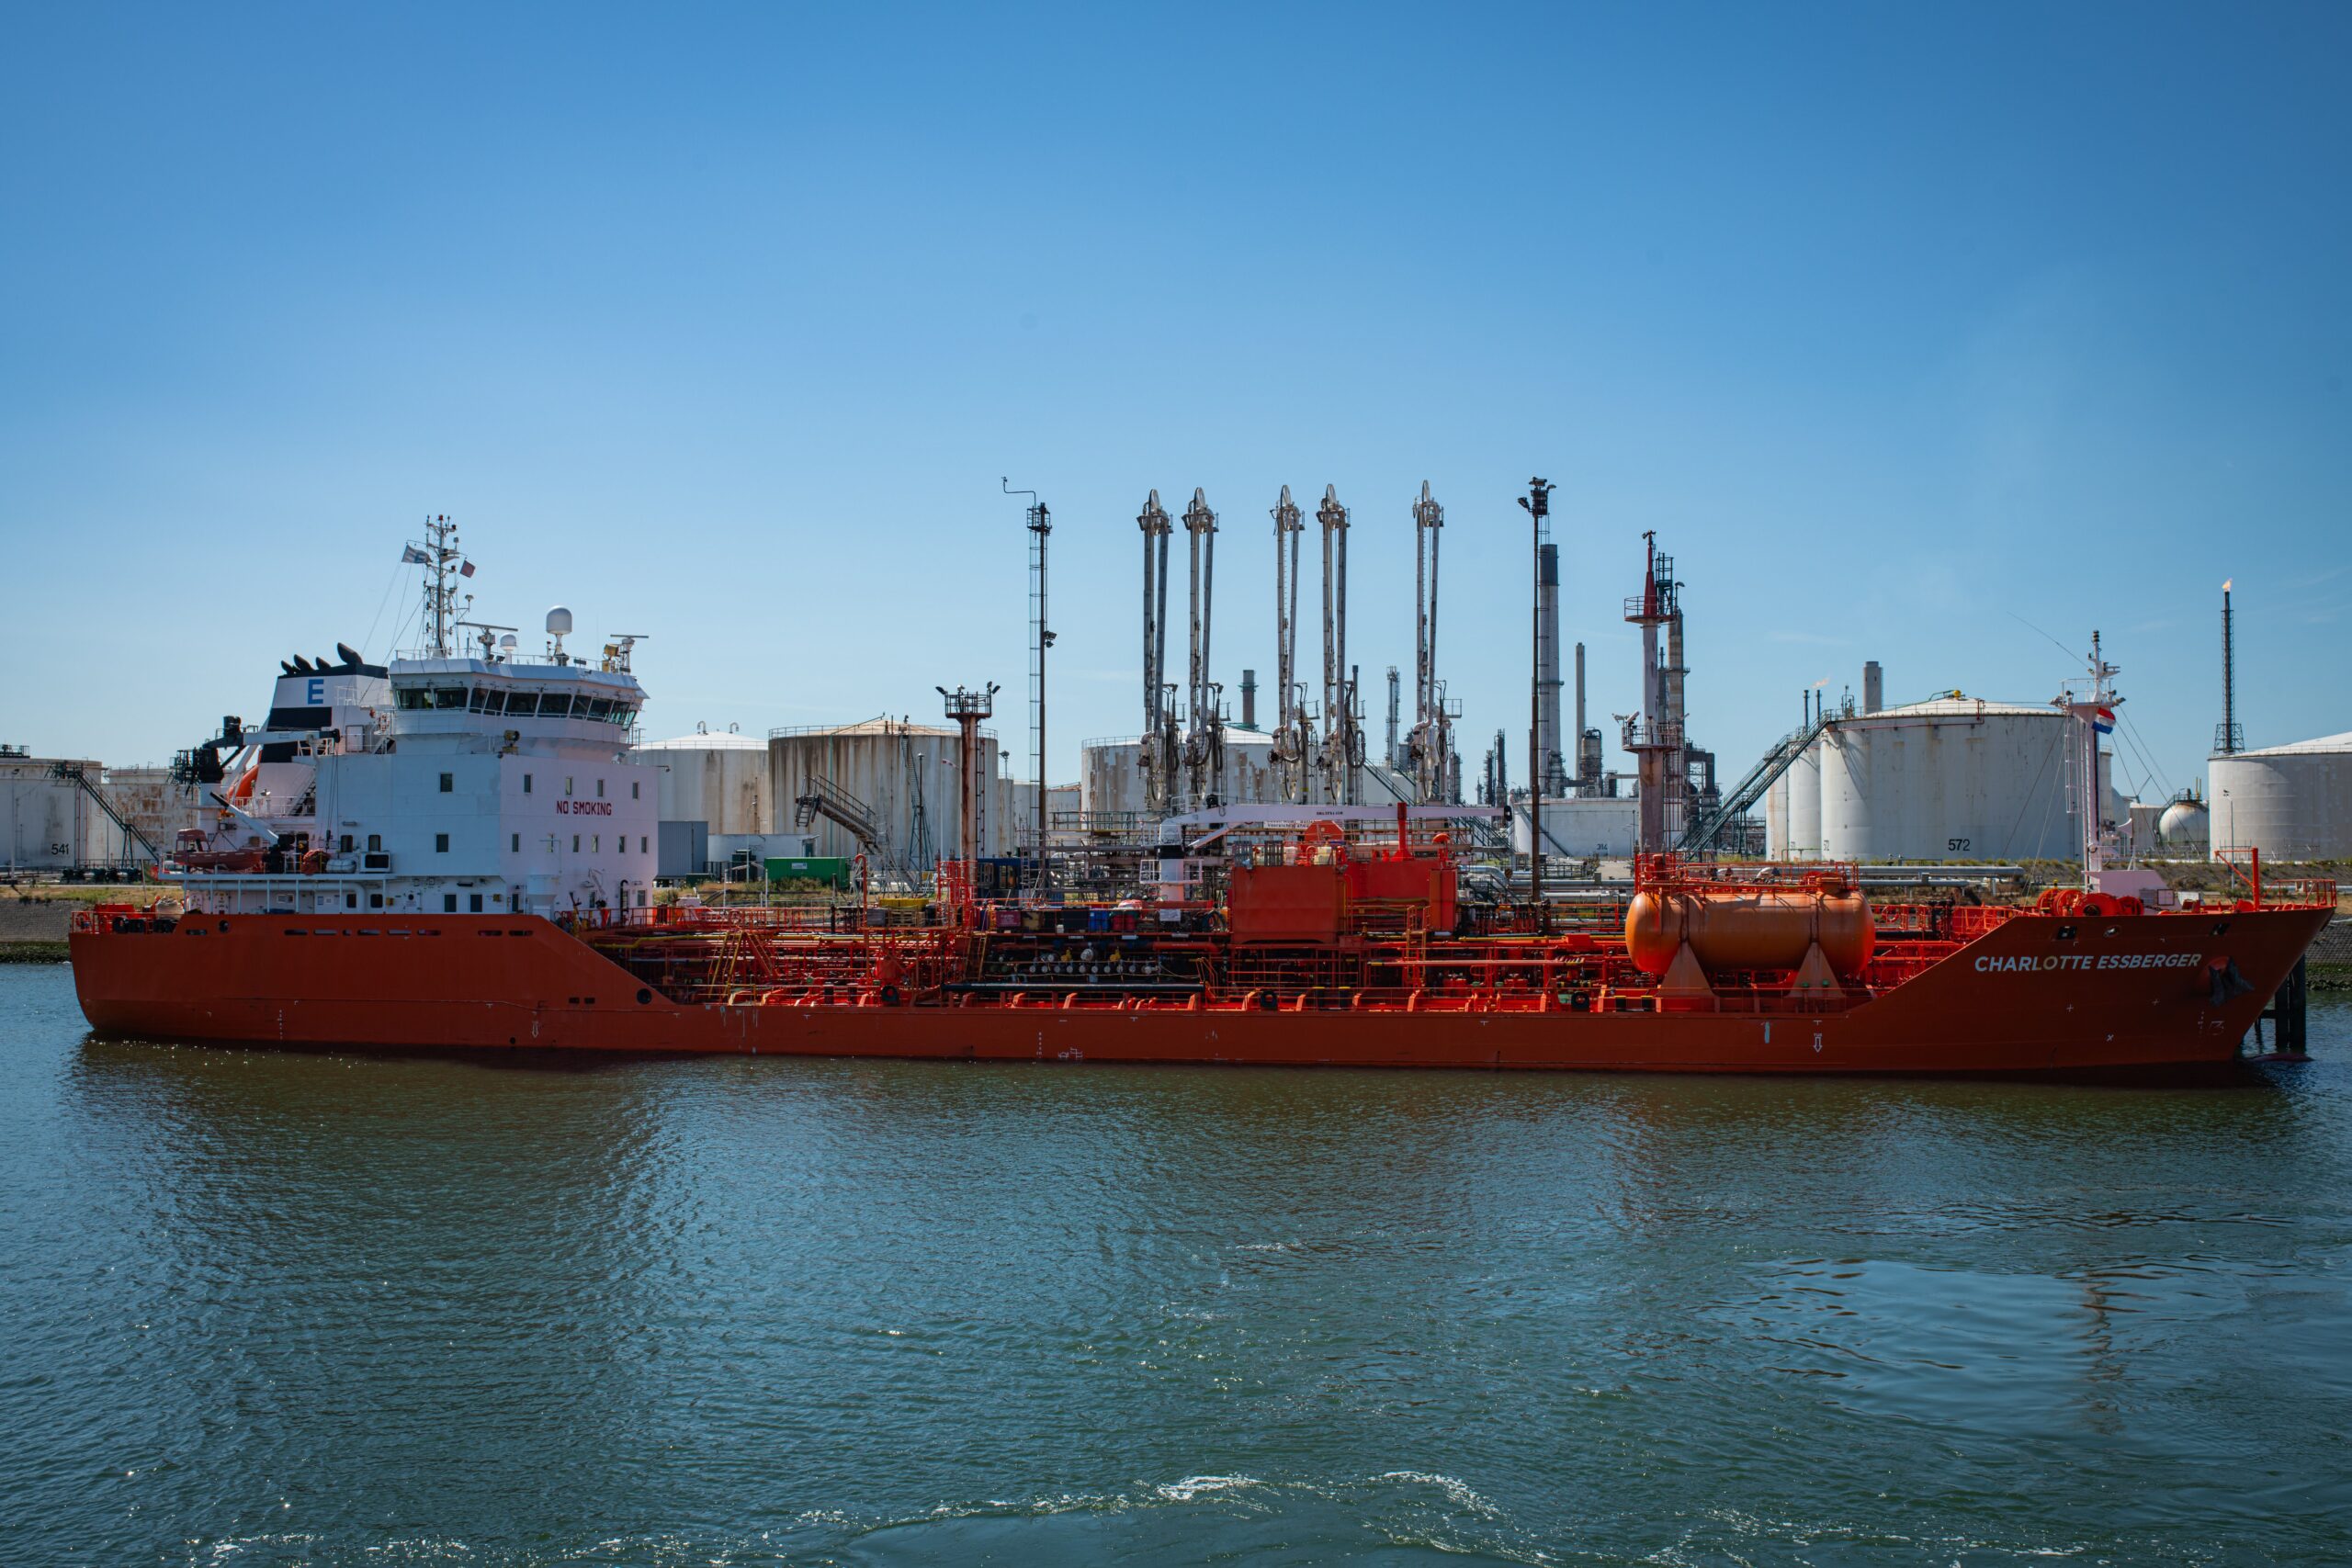
Chemical and palm oil cargoes moving around Asia are facing higher tanker freight costs as vessel availability remains tight despite additional ships entering the market. Freight assessments for most intra-Asia liquid bulk routes rose during the two weeks to 28 October, with palm oil voyages from Southeast Asia to India and China reaching levels last seen more than three years ago.
Market intelligence group ICIS identifies several pressures acting at once: port congestion is tying up vessels, fuel has become more expensive, and owners are reluctant to commit some available space at current spot quotations. The rise has continued even after the pre-Diwali restocking surge in India began to fade, indicating that tight shipping conditions extend beyond a single seasonal buying period.
Malaysia’s palm oil exports increased in the first half of October, with the reported month-on-month rise varying across the measurements cited by ICIS from 43.2% to 58.3%. Pre-Diwali buying in India and activity among Chinese buyers added cargo demand. Concerns about dry conditions affecting production in Malaysia and Indonesia into 2027 are also encouraging some traders to bring purchases forward, increasing competition for suitable vessel space.
Available tanker capacity depends on the location and readiness of individual ships as much as on total fleet numbers. A chemical cargo requires suitable tanks, an acceptable cargo history and a vessel available within the loading window. Ships delayed at ports or occupied on longer voyages cannot accept another shipment at the same time, reducing prompt capacity even while new tankers are being delivered to the wider fleet.
Port delays have become an important constraint around Southeast Asia and India. Tankers held at anchor awaiting an available berth are effectively removed from the immediate supply of shipping capacity until they discharge or load and complete the necessary terminal procedures. ICIS cites an instance of gasoline blending cargoes waiting more than ten days for a berth at a petrochemical hub, illustrating how congestion can hold up specialised vessels and delay their next employment.
Small chemical parcels often share a tanker with other compatible grades, separated in individual cargo tanks. Each shipment must satisfy its tank-preparation and segregation requirements and fit a sequence of port calls. Unreliable arrival and loading windows make it harder to assemble several such parcels on one rotation, reducing practical booking options even when some nominal capacity is still available.
Shipowners are also responding to higher returns in other liquid bulk trades. Some clean-product tankers have moved towards crude or dirty-product employment, reducing the ships available for their former cargoes. Tank compatibility, cleaning standards and certificates still govern which transfers between cargo types are possible, so the resulting capacity pressure differs among chemical, petroleum and edible oil routes.
Marine fuel costs add pressure at the same time. The Singapore bunker market recorded substantial price increases during October, pushing up one of the variable costs of a voyage. The burden is influenced by fuel consumption, sea distance, waiting time and the commercial terms of the charter. An owner quoting for a route must consider not only the outward voyage but also where the ship is likely to find its next suitable cargo.
Southbound chemical routes associated with gasoline blending have outperformed northbound and some shorter intra-regional movements. The difference reflects the cargo enquiries and vessels available on each lane. Freight assessments therefore vary by origin, destination, shipment size and loading window; the upward regional trend does not translate into one uniform rate for every chemical parcel.
India and China remain central destinations for Southeast Asian palm oil, with shipments tied to food production, industrial processing and other downstream uses. Cargo buyers need to combine their purchase commitments with vessel availability and receiving-tank capacity. An unexpectedly expensive freight fixture can change the delivered cost of a consignment, while a delayed arrival may alter the timing of feedstock availability to the receiving business.
Part-parcel shipments become harder to assemble as prompt space tightens, because the shipper must find a vessel already calling at appropriate ports with compatible spare tank capacity. That reduces the combinations of loading date, transit time and rate available for negotiation. Consolidating parcels or changing loading windows can alter the commercial outcome, but storage limits and delivery commitments restrict the options.
The current conditions contrast with the earlier expectation that substantial new tanker deliveries would ease regional freight costs during 2026. Additional ships increase nominal fleet size, yet the effective supply available on each route still depends on delays, cargo competition, positioning and operating costs. The distinction is already visible in October’s market assessments, which remained elevated after some seasonal restocking demand subsided.
The next commercial test will be whether vessels become available more readily as November shipments are booked and congested ports clear their queues. ICIS’s late-October assessments establish an upward movement across many regional routes, but the outcome for individual freight contracts will continue to depend on cargo type, voyage, loading window and the particular vessel offered.