IN Brief:
- GXO targets organic revenue growth above 7% annually from 2027 through 2030, compared with initial guidance above 5.5% for 2027.
- The company is targeting an adjusted EBITA margin above 6.5% by 2030, supported by operating standardisation and automation.
- Data centres, aerospace and defence, life sciences and industrial logistics are priorities, while projected financial outcomes remain unachieved targets.
GXO Logistics has set a target of more than 7% compound annual organic revenue growth for 2027–2030, supported by further expansion in specialist industrial logistics and a wider rollout of warehouse technology. At its Investor Day on 16 November, the company also set an adjusted EBITA margin target above 6.5% by 2030. Adjusted EBITA means earnings before interest, taxes and amortisation after the company’s specified adjustments. Both figures are forward-looking targets, not achieved results.
For 2027, GXO forecasts organic revenue growth above 5.5%, an adjusted EBITDA margin above 7.1%, and an adjusted EBITA margin above 4.5%. The four-year ambition implies faster average organic growth after that initial year and improved returns from existing as well as new operations. Customer mix, operational standardisation and technology form the stated route to the targets, although the company cannot yet assign a verified share of future margin improvement to individual initiatives.
GXO is concentrating commercial effort on data centres, aerospace and defence, life sciences and industrial logistics. These activities involve different handling and control requirements from conventional consumer fulfilment. Aerospace components can require traceable serial-number records and carefully controlled storage, while life sciences contracts may need validated temperature conditions and regulated inventory processes. Data centre equipment presents another set of requirements around delivery sequencing, physical security and the handling of high-value infrastructure components.
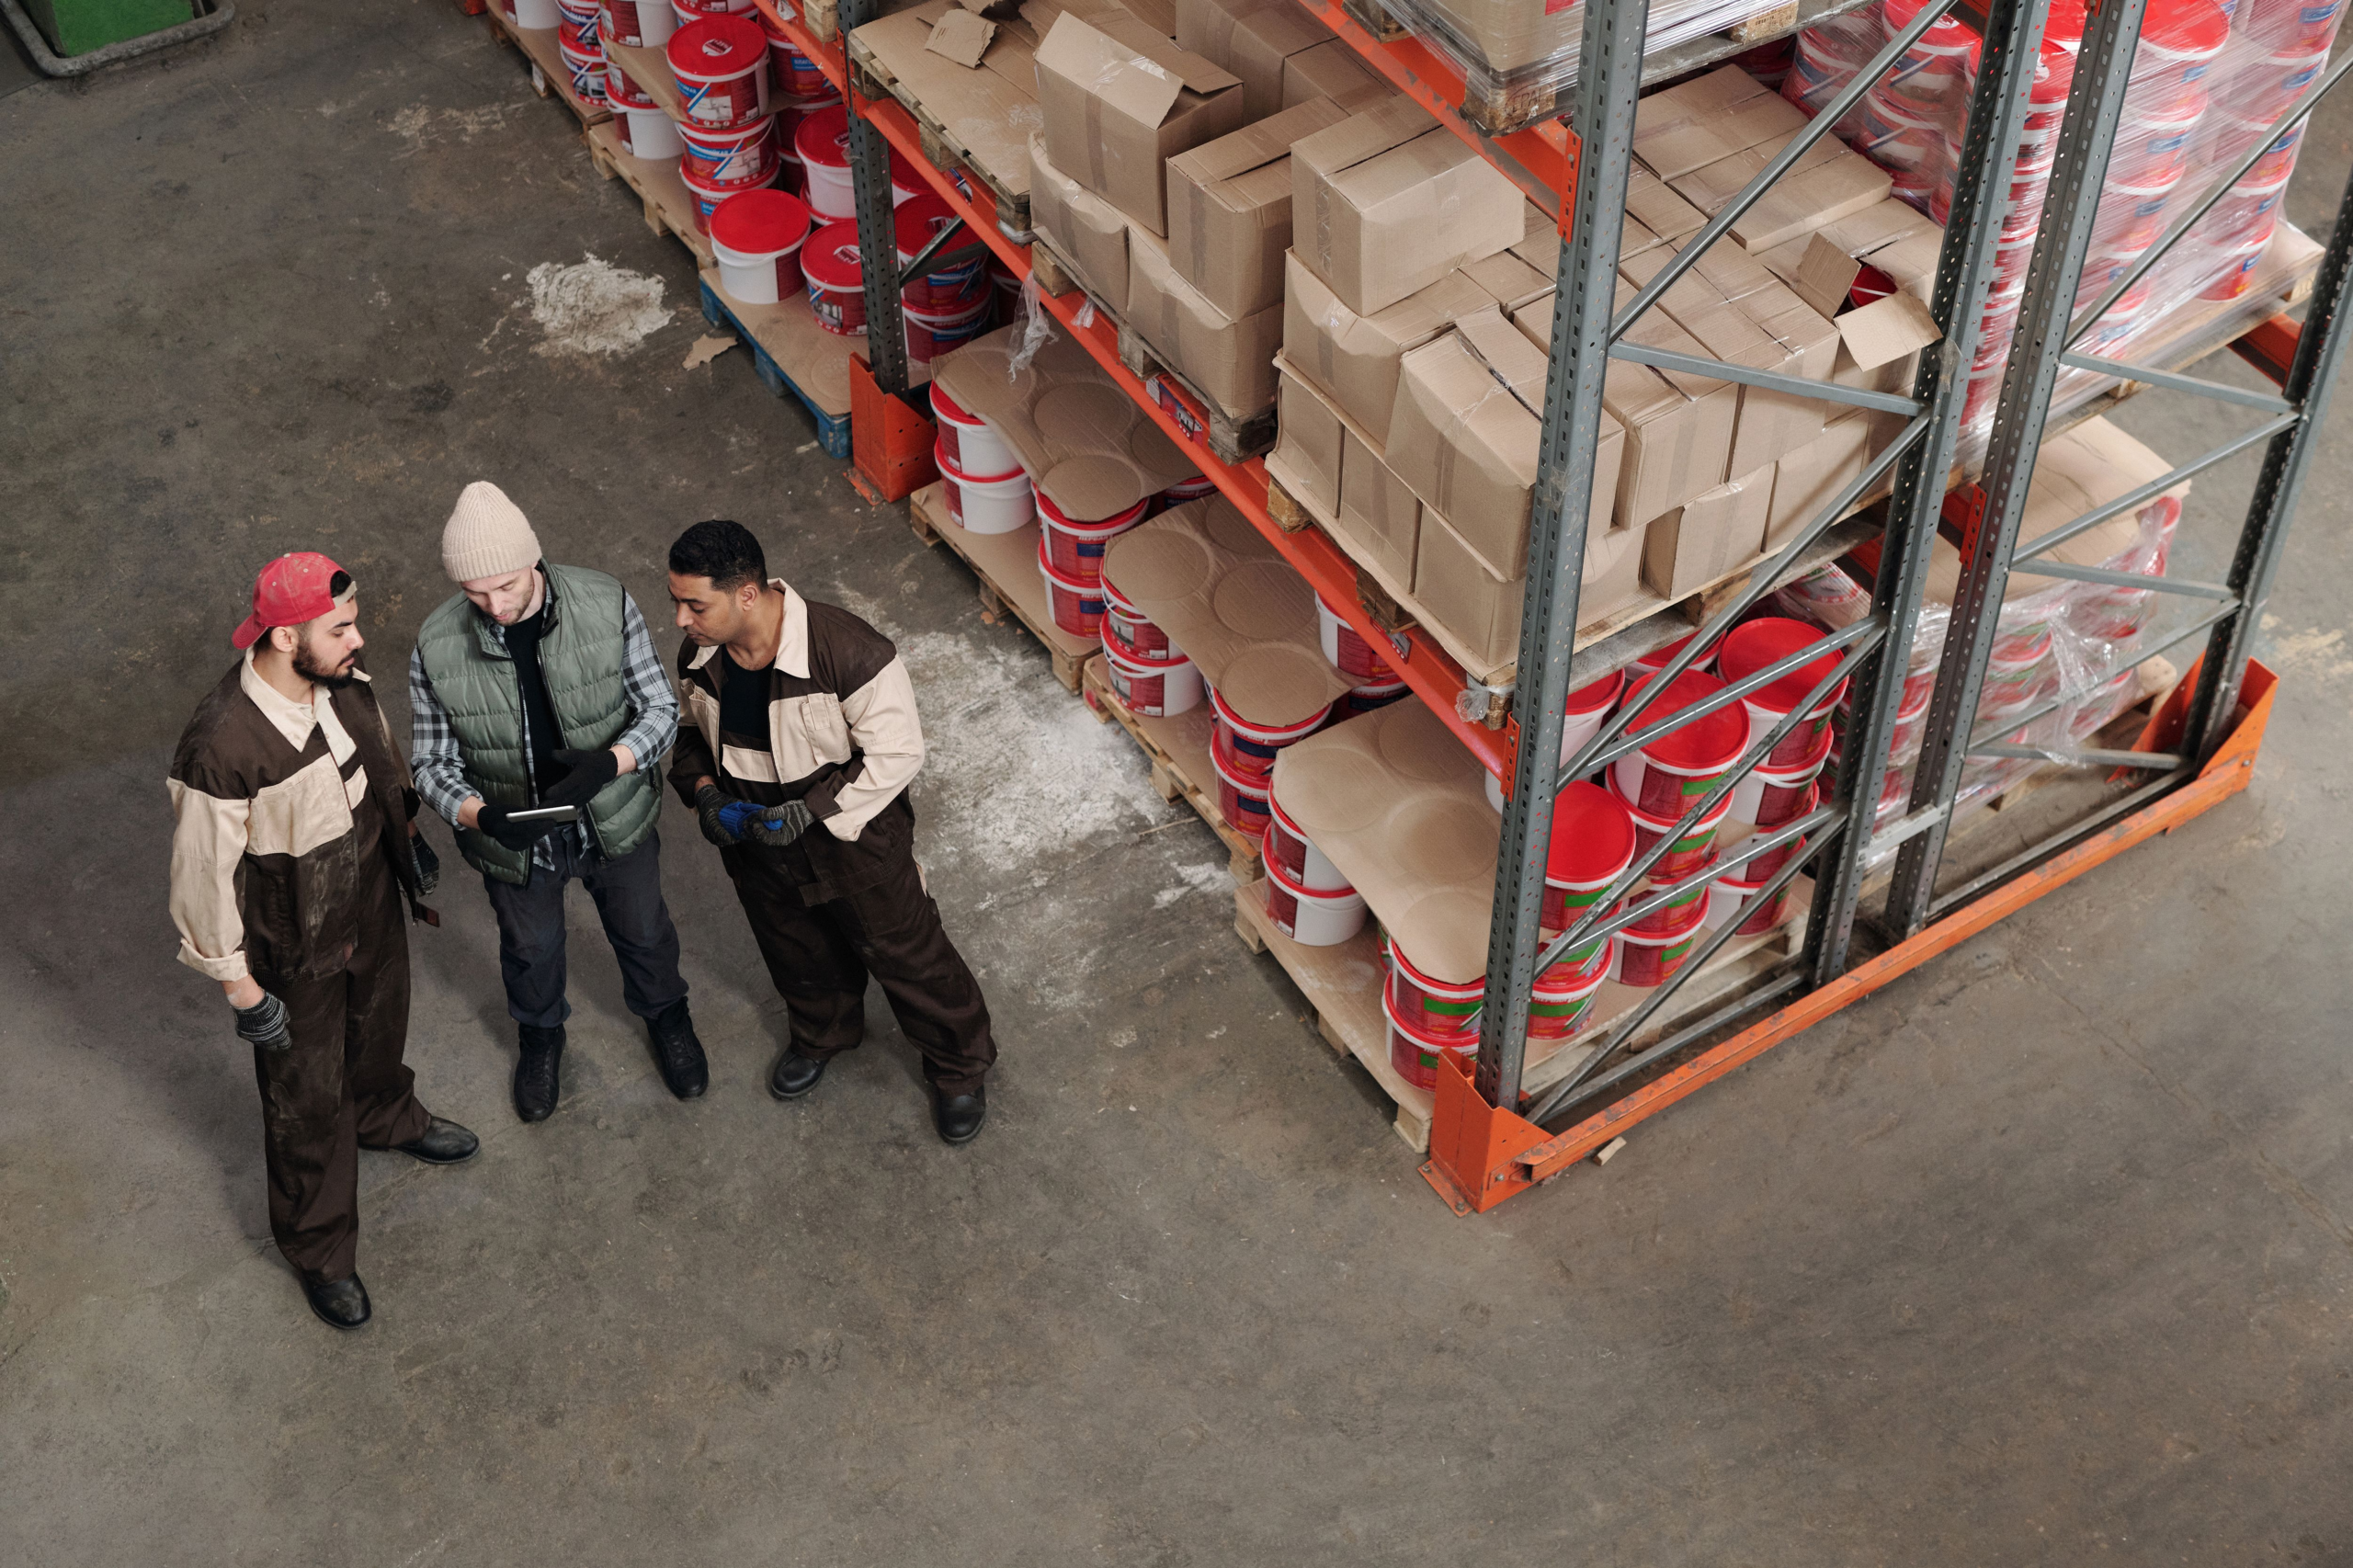
Retail and consumer fulfilment will remain substantial activities within GXO’s network. Management is seeking additional contracts in sectors where storage, handling and delivery requirements are more specialised, alongside extensions of existing customer relationships. Such contracts can involve dedicated facilities, controlled inventory processes and carefully sequenced deliveries rather than only higher volumes of conventional picking and dispatch.
A contract logistics provider is paid to operate agreed parts of a customer’s supply chain, which can include warehouse management, labour, materials handling, returns, inventory control and transport coordination. Expanding a customer relationship may involve taking on additional facilities, handling different product groups or introducing more technology at an existing site. Revenue then depends on the services actually delivered and the contract’s charging structure, not simply the announced value of a customer’s wider logistics expenditure.
GXO intends to standardise labour management, purchasing and site performance through its GXO Way operating approach. The labour management component can compare recorded work with the resources allocated to particular tasks, while common procurement practices can affect the cost of equipment and services bought across the network. Differences in customer contracts and operating configurations still need to be accounted for before comparing one warehouse’s productivity with another’s.
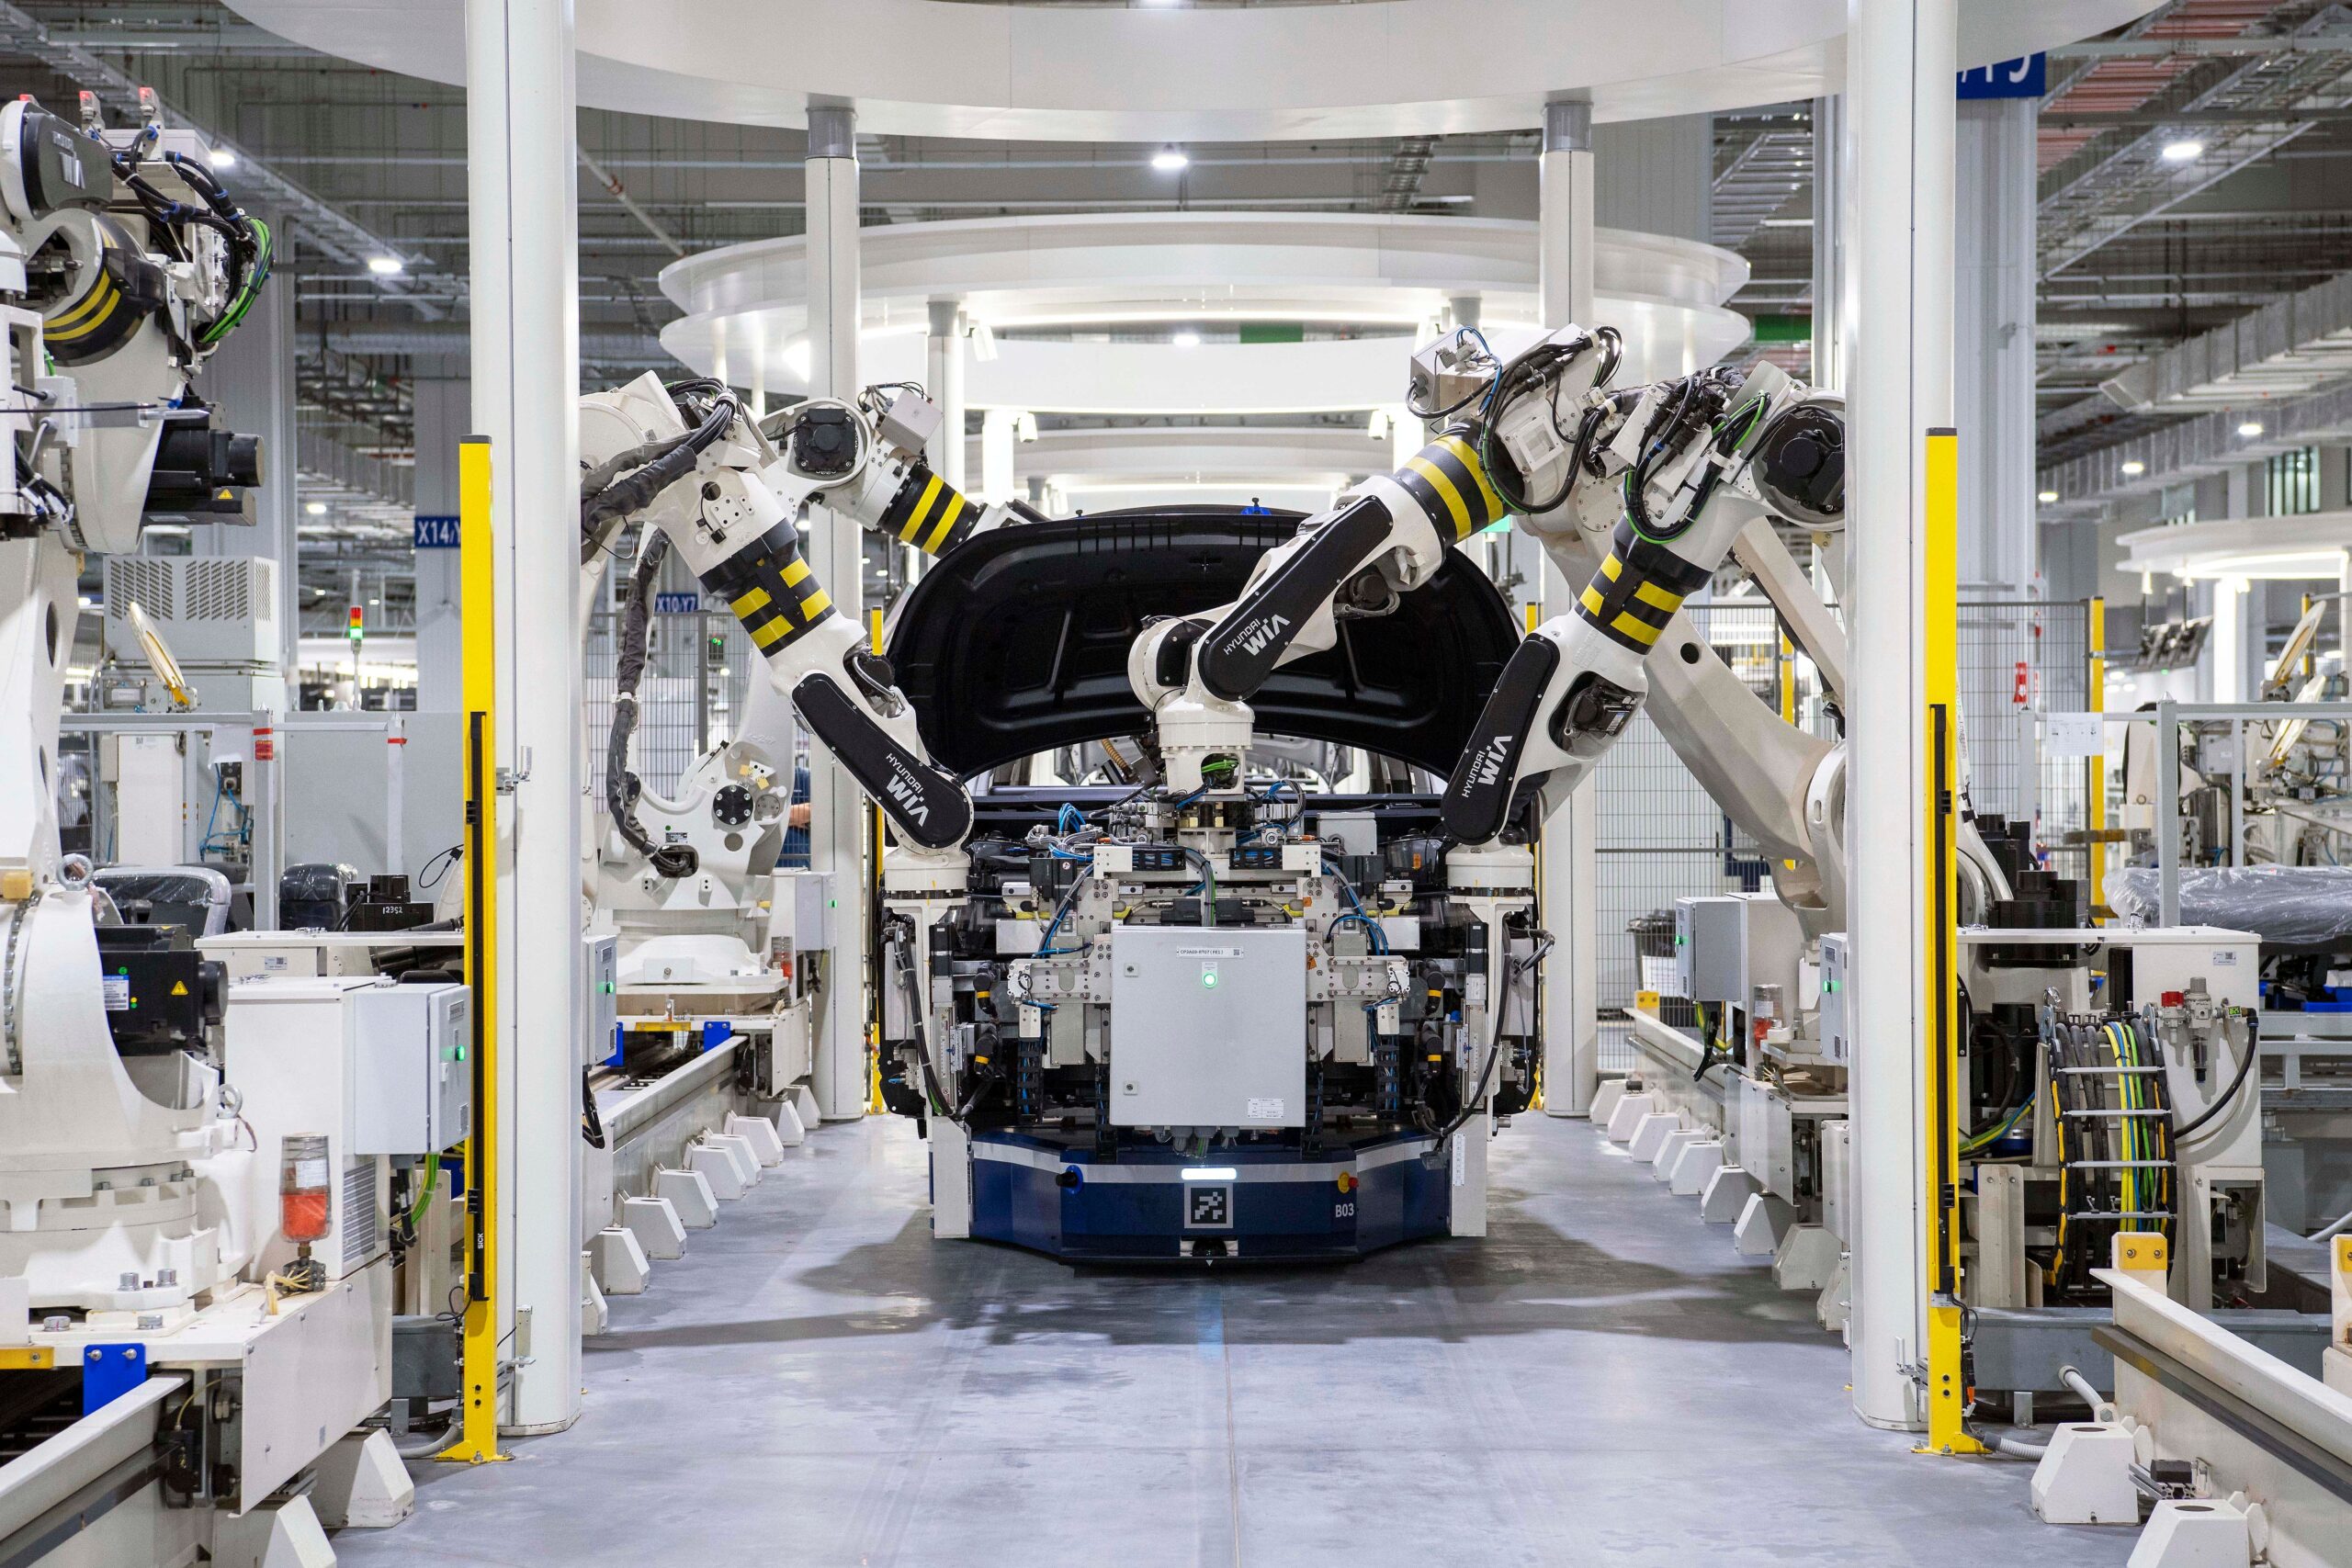
The group also plans to expand GXO IQ, its warehouse technology platform, to more than 400 locations by the end of 2030. Its investor materials envisage approximately 120 sites by the end of 2027. GXO is positioning the platform to support repeatable software and artificial intelligence applications across multiple operations; those installation figures remain targets. Integrating each site will depend on the warehouse management system, the installed handling equipment and the data available from customer processes.
Warehouse software has to coordinate information from several layers of the operation. Customer orders and inventory obligations sit in warehouse management applications; labour scheduling establishes the people available to carry out tasks; and robotics or conveyor controls report equipment status and movements. A forecasting or task-allocation tool must work with current data from those systems to be useful. Where information is late, inconsistent or incomplete, an automated recommendation can create queues or misplaced priorities instead of removing them.
Specialist customer requirements complicate standardised rollout. Pharmaceutical stock can require auditable temperature records and controlled handling; aerospace components may move through inspection and quarantine steps before issue; and deliveries of data centre equipment depend on installation readiness and security arrangements at the receiving site. Common software must therefore support local exceptions, traceability rules and contractual service levels instead of treating every inventory movement as interchangeable.
GXO projects more than 240 basis points of adjusted EBITA margin expansion between its 2025 baseline and 2030. Its investor presentation identifies a higher-margin customer mix, commercial discipline, procurement savings, labour productivity, warehouse technology and administrative efficiencies as contributors. An adjusted EBITA margin is a non-GAAP measure; the target should not be presented as equivalent to statutory operating profit or to net cash generated by every logistics contract.
The company is additionally targeting free cash flow conversion of 40%–50% relative to adjusted EBITDA. It expects to hold capital expenditure at about 2%–3% of revenue while increasingly using customer-funded automation and completing integration work linked to earlier acquisitions. The resulting cash outcome depends on working capital, capital spending, contract terms and other costs. The percentage is a financial objective, not a reported cash conversion rate achieved in 2026.
GXO reported approximately US$3.6bn of third-quarter revenue earlier in November, with organic revenue growth of 6.4%. Those results provide a current operating baseline for the new plan, not evidence that the 2030 targets have been achieved. Subsequent financial statements, warehouse deployments and contract performance will show whether specialist-sector growth and standardised operations are delivering the expected gains in margin and cash flow.