IN Brief:
- PortCalls reports PIDS researcher Jose Ramon Albert modelling freight-cost pressures of roughly 9–14%; the unpublished slides have not been independently checked.
- The event organiser confirms the 9 October presentation; mode-specific petroleum shares and costs are attributed to on-the-scene reporting.
- The scenarios use reported 2018 input-output data and should not be treated as observed freight rates or firm-specific forecasts.
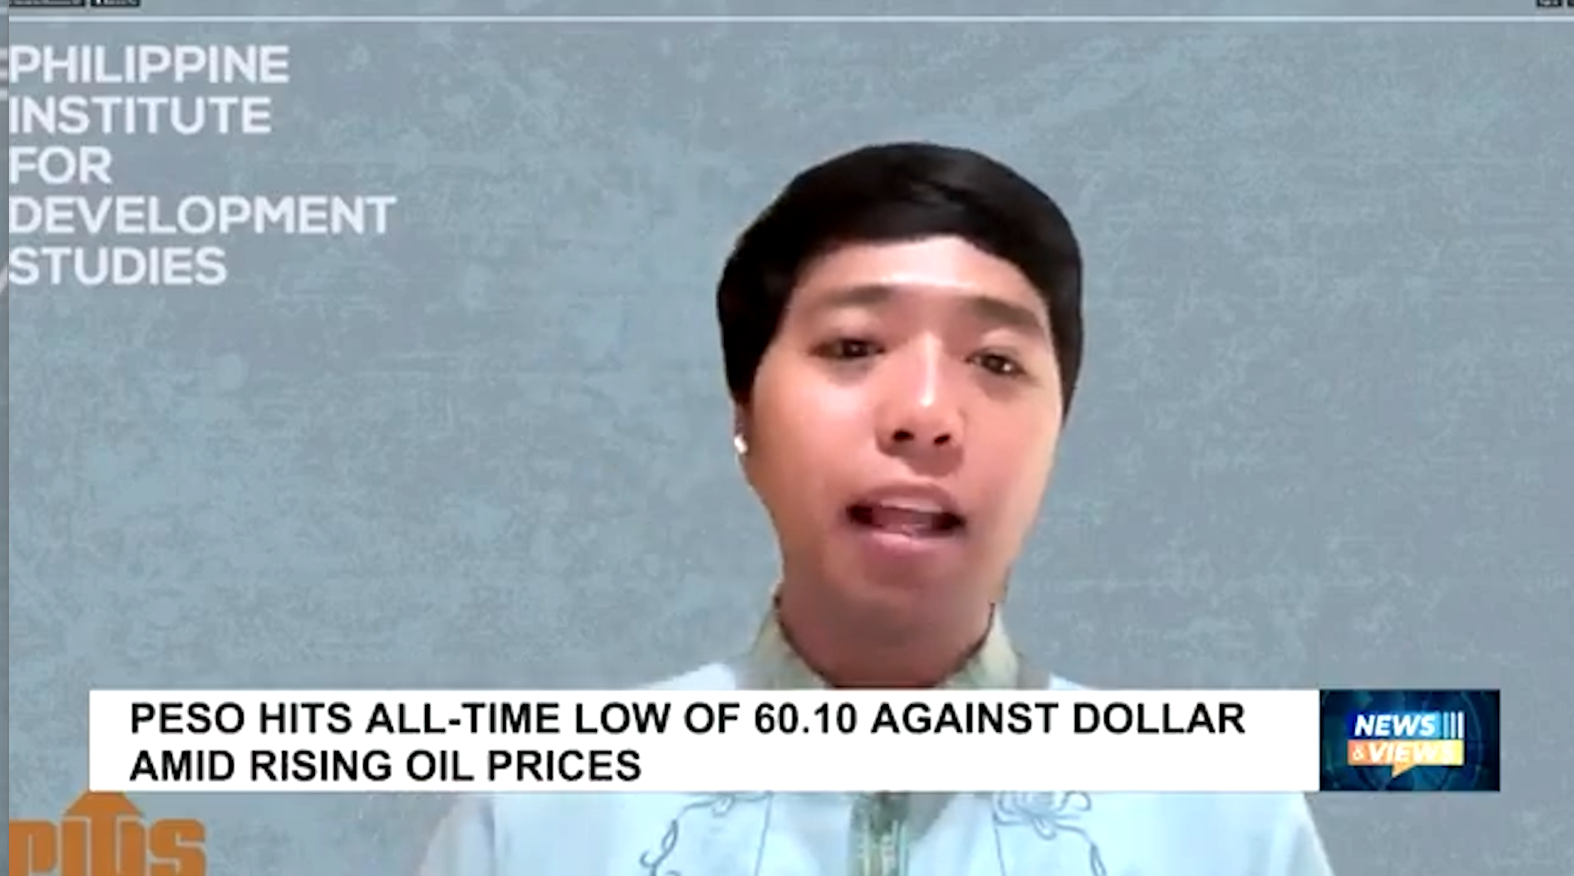
Research presented at a supply chain conference in Manila suggests that a sustained oil-price shock could raise freight costs in the Philippines by approximately 9% to 14%, with the effect differing significantly across transport modes and industrial customers. The event organiser’s published programme confirms that Jose Ramon Albert, senior research fellow at the Philippine Institute for Development Studies (PIDS), presented a session entitled “The Impact of the 2026 Oil Price Shocks on the Business Sector” at PASIAWORLD 2026 on 9 October. The figures were described by specialist publication PortCalls in on-the-scene reports dated 12 October. The underlying presentation and model files are not publicly available for independent inspection, and the estimates describe scenarios rather than freight-rate increases already recorded in the market.
According to PortCalls’ account of Albert’s presentation, the analysis uses three oil-price scenarios developed by the Asian Development Bank to examine how fuel costs move through the wider Philippine economy. Its baseline case uses crude prices of approximately $100 per barrel, while the most severe case assumes $125 per barrel and a crisis lasting until March 2027. These are modelling assumptions, and their resulting estimates should not be presented as a forecast with a guaranteed probability or as a description of current contract rates.
PortCalls reported Albert’s modelled additional economy-wide production costs as approximately ₱550 billion under the baseline case, ₱942 billion if disruption persists and as much as ₱1.3 trillion in the most severe scenario. The figures represent alternative estimated burdens rather than amounts to be added together. Albert also outlined possible effects on GDP growth and inflation, emphasising that some higher costs could be absorbed through reduced business margins while others could be reflected in prices paid by customers.
Transport operators are exposed directly to the price of petroleum, but not all modes have the same cost structure. In the reporter’s account, Albert placed petroleum at approximately 23% of air transport production costs, compared with around 12% to 13% for land and water transport. The same report puts the baseline modelled increases at 14.4% for air transport and 9.8% for land transport. The reported severe-case air transport increase exceeds 30%, but none of these conference figures has been independently recalculated or validated against the original PIDS slides.
The reported 9–14% indicative freight-cost range could affect routes connecting the Philippines’ major islands, where domestic shipping and air services are integral to moving industrial supplies and finished goods. A route involving domestic shipping or air freight can carry a larger fuel-related cost burden than an equivalent movement handled entirely near a manufacturing centre or urban distribution hub. PortCalls reported Albert warning that shipments to the Visayas and Mindanao could face disproportionate pressure. That assessment indicates potential exposure; it is not a verified regional price comparison for individual services.
Fuel-driven pressures extend into the cargo itself. The original conference coverage attributes further baseline industry estimates to Albert: 14.6% for basic metals, 11.8% for cement, 5.8% for paper and packaging, 3.8% for electronics and 1.9% for food products. Those increases concern industry input costs, not the percentage by which retail prices or cargo rates would automatically rise. The commercial outcome will depend on purchasing agreements, inventory policy, market competition and how much cost each participant can absorb.
Existing freight and supply contracts differ in how and when carriers can pass on additional fuel costs. A supplier or haulier committed to a fixed price may be unable to pass through a rapid fuel-price increase until a contract is renewed, potentially eroding its margin or financial capacity. Contracts with explicit fuel adjustment mechanisms can distribute that pressure differently, although their reference indices and adjustment schedules matter. Any renegotiation must distinguish between the operator’s actual fuel expenditure and wider cost estimates derived from the economy-wide model.
PortCalls also describes Albert presenting a separate analysis using business survey data across roughly 250 detailed industry codes. The reporter gives total firm fuel expenditure as ₱323.6 billion and an average transport-sector fuel intensity of about 22%, compared with an aggregate ratio of approximately 1.56% across the surveyed industries. These unexamined presentation figures need attribution, and should not be presented as confirmed by an accessible PIDS dataset. This is a different measurement from the input-output scenario estimates and should not be added to the projected production-cost burdens.
PortCalls also relays a methodological limitation noted by Albert: industry linkages were drawn from a 2018 input-output table, which may not fully describe changes in sourcing, transport patterns and domestic production since the pandemic. Without the original slide deck or model documentation, the exact sensitivity assumptions and calculations cannot be reproduced independently. The model is useful for identifying likely areas of exposure and relative sensitivity, but current invoicing data, updated sector weights and individual fleet fuel consumption would be needed before converting it into a company-level cost forecast.
According to the reporter’s account, Albert called for more detailed land transport data and targeted assistance rather than undifferentiated support across every industry. The presentation also pointed to working-capital needs among smaller businesses and the importance of reducing dependence on imported fuel over time. In the nearer term, logistics operators and cargo owners can use the scenarios to test contract clauses, working-capital requirements and delivery costs under several fuel assumptions. Whether freight ultimately rises by the figures modelled will depend on the scale and duration of the shock and how costs are shared throughout supply chains.