IN Brief:
- The Port of Long Beach handled 919,992 TEU in August, up 2% from the same month in 2025.
- Loaded imports increased 3.6% to 456,100 TEU and exports rose 4% to 99,754 TEU.
- Throughput reached 6,678,078 TEU over the first eight months of 2026, 1.3% ahead of the same period last year.
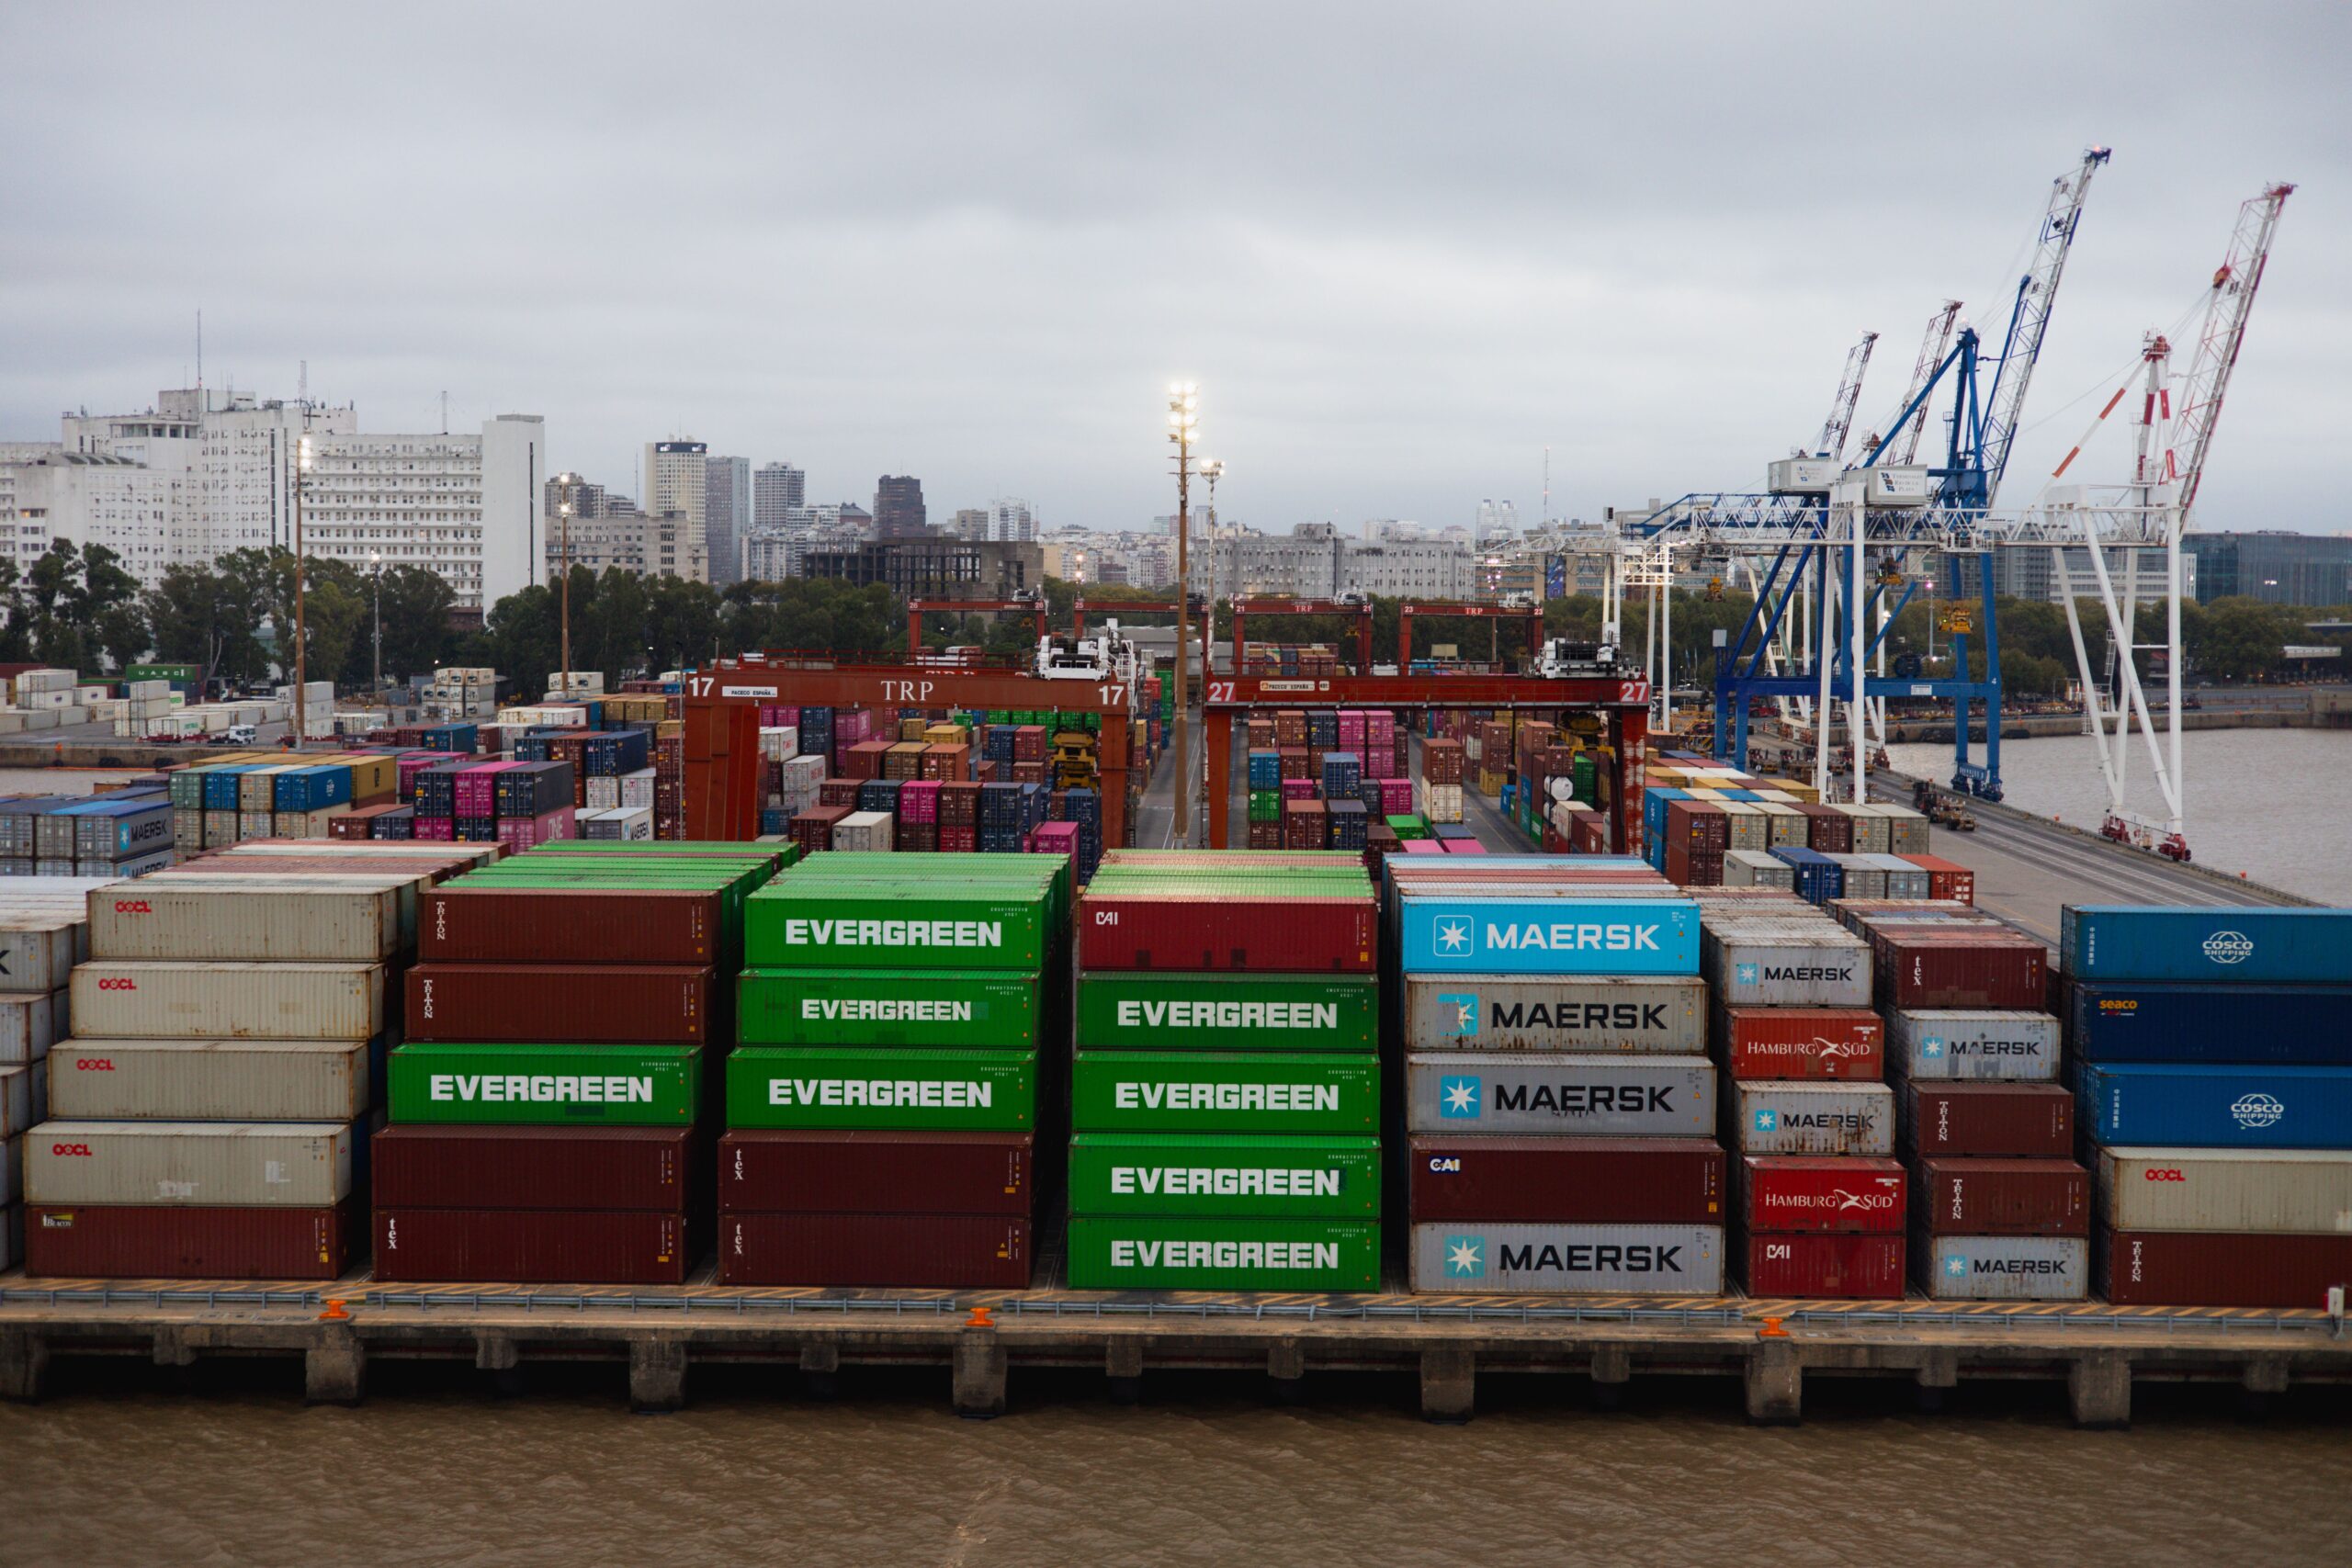
The Port of Long Beach handled 919,992 TEU in August, recording the busiest August in its 115-year history and the fifth-highest monthly container total the Californian gateway has handled.
Total throughput increased 2% from August 2025. Loaded imports rose 3.6% to 456,100 TEU, loaded exports increased 4% to 99,754 TEU, and empty-container movements declined 0.39% to 364,138 TEU.
Across the first eight months of 2026, Long Beach handled 6,678,078 TEU, 1.3% more than during the same period last year. The year-to-date figure shows continued growth without matching the scale of the monthly record, reflecting the uneven way cargo has moved through the US import cycle during 2026.
Port management has linked the August volumes to the way shippers are responding to tariffs and geopolitical uncertainty. Importers have spent much of the year adjusting shipment timing around changing trade costs and the risk of disruption, making the conventional peak-season calendar less reliable as a guide to when containers will arrive.
That pattern has already been visible in national forecasts. Earlier US import analysis pointed towards weaker container volumes later in 2026 after companies brought some cargo forward. Long Beach’s August result does not invalidate that national direction, but it shows how the effect can be distributed unevenly between gateways and months.
Port-level capacity has to respond to the containers arriving locally rather than to a national average. A market can be softening overall while a particular terminal still faces concentrated vessel calls, high yard occupancy, or pressure on drayage and rail connections. Record throughput therefore remains an operating issue even when the wider import outlook is becoming less buoyant.
The split between loaded and empty containers is also significant. Empty boxes accounted for 364,138 TEU in August, close to 40% of total container movements. They do not carry customer cargo, but they still require crane moves, yard space, vessel slots, and transport planning because equipment has to be repositioned to locations where exporters and overseas factories need it.
Loaded imports remained the largest individual category at 456,100 TEU. Those containers feed into Southern California warehouses, rail terminals, distribution networks, and transport links serving markets well beyond the immediate port region. High import months consequently create demand across several layers of inland logistics rather than ending once a box leaves the marine terminal.
Bringing cargo forward can protect a supply chain from an anticipated tariff change or transport disruption, but it moves pressure elsewhere. Goods arriving earlier spend longer in inventory unless demand has also shifted forward, increasing warehouse occupancy and tying up working capital. The risk avoided at the border can therefore reappear as a storage and forecasting problem inland.
The change in shipment timing also affects labour and transport planning. Drayage fleets, warehouses, rail operators, and distribution centres typically prepare for recognisable seasonal peaks. When importers move orders in response to policy deadlines or geopolitical events, those peaks can arrive earlier, extend for longer, or break into several surges.
Long Beach’s empty-container volume adds another planning layer because export equipment has to be repositioned while import boxes are flowing inland. A gateway handling both record loaded volumes and substantial empty movements needs yard and vessel capacity for both tasks, even though only one represents merchandise entering or leaving the country.
The August figures are confirmed by the port’s own monthly statistics, which list 919,992 total TEU compared with 901,846 in August 2025. The result places the month within a broader period of high activity rather than as an isolated statistical anomaly.
The port is expected to provide further discussion of the cargo figures during its next Supply Chain Insight briefing. More detail on customer behaviour and shipment timing could help distinguish between normal seasonal demand, cargo brought forward against policy risk, and volume captured from competing gateways.
The next several months will provide the clearer test. If national imports weaken while Long Beach remains at elevated levels, the port may be gaining share or receiving cargo whose timing has shifted relative to other gateways. If throughput falls with the broader market, August will look more like the upper end of an extended 2026 peak.
Either way, the 919,992 TEU result shows that a softer national forecast does not translate automatically into lower operating pressure at an individual port. Warehouses, transport providers, and cargo owners connected to Long Beach still have to plan around the physical arrival pattern at the gateway, and August delivered more containers than any previous August in its history.