IN Brief:
- GEODIS launched a US Final Mile Index with a Q3 2026 reading of 149.8 on a 2019 baseline of 100.
- The index rose 10.5% year on year; its B2B local freight component rose 10.7% and parcel/courier component 10.2%.
- GEODIS expects a Q4 reading above 145 but presents that figure as a forecast rather than a realised outcome.
GEODIS has launched a quarterly measure of US final-mile delivery prices, putting the third-quarter 2026 index at 149.8 against a 2019 baseline of 100. The index rose 10.5% from a year earlier and stands 49.8% above its baseline. GEODIS compares that change with consumer price inflation of 3.5% over the year and 30.8% cumulatively since 2019. The figures measure different baskets and should not be treated as a direct comparison of individual freight invoices and consumer purchases.
The composite uses two US Bureau of Labor Statistics Producer Price Index series: couriers and messengers, broadly representing parcel delivery, and local general freight trucking, used for business-to-business and larger-item movements. GEODIS rebases the two series to 2019 and weights them equally. In Q3, the courier component reached 163.5, up 10.2% year on year, while local freight reached 136.0, up 10.7%. The composite can show broad price pressure across those categories but cannot establish the change paid by one shipper on a particular contract.
September’s index reading reached 152.0, the highest monthly figure in the series as presented by GEODIS. Monthly peaks can differ from quarterly averages because freight demand, operating costs, and pricing arrangements do not move uniformly through a season. A shipper assessing its own invoices needs to compare the same lane, delivery service, shipment profile, and contracted surcharges over time. Otherwise, a shift towards heavier or harder-to-handle deliveries could be mistaken for a pure increase in the underlying unit price.
The published index also sets out operating risks that can raise the total cost of delivering a consignment beyond the contracted transport charge. Fuel, driver availability, theft, cargo damage, and missed delivery windows affect different parts of a freight transaction. A carrier may pass higher fuel costs into a surcharge, while an insurer or shipper may bear part of a theft or liability loss. Those exposures require separate measurement rather than being added automatically to the index’s base price movement.
Fuel has been a particularly volatile input. GEODIS cites a retail diesel price of $6.53 per US gallon on 21 September, 74% above the comparable year-earlier level, and expects the effects of the September increase to feed into later fuel surcharges. The actual lag depends on each carrier’s published surcharge schedule or contractual calculation method. A change in the price of diesel on one date will not necessarily alter every final-mile invoice immediately or by the same percentage.
The operator expects the composite index to remain above 145 in the fourth quarter as fuel surcharges and peak-season charges continue. That is a forecast, not an observed Q4 outcome. A final reading could differ as fuel prices, shipment patterns, and contract terms change through November and December. The 2019 baseline also means a reading of 145 would still represent a substantial increase compared with the start of the index, even if it were below the Q3 result.
GEODIS separately cites Verisk CargoNet data for 677 theft incidents across transport modes in Q2 2026, 26% fewer than the comparative figure, while estimated losses increased to $304.6 million from $135.7 million. Fewer events accompanied by higher reported losses can reflect changes in the value or type of goods targeted. This is a separate security dataset, not a count of thefts confined to final-mile operations or a component of the producer price index.
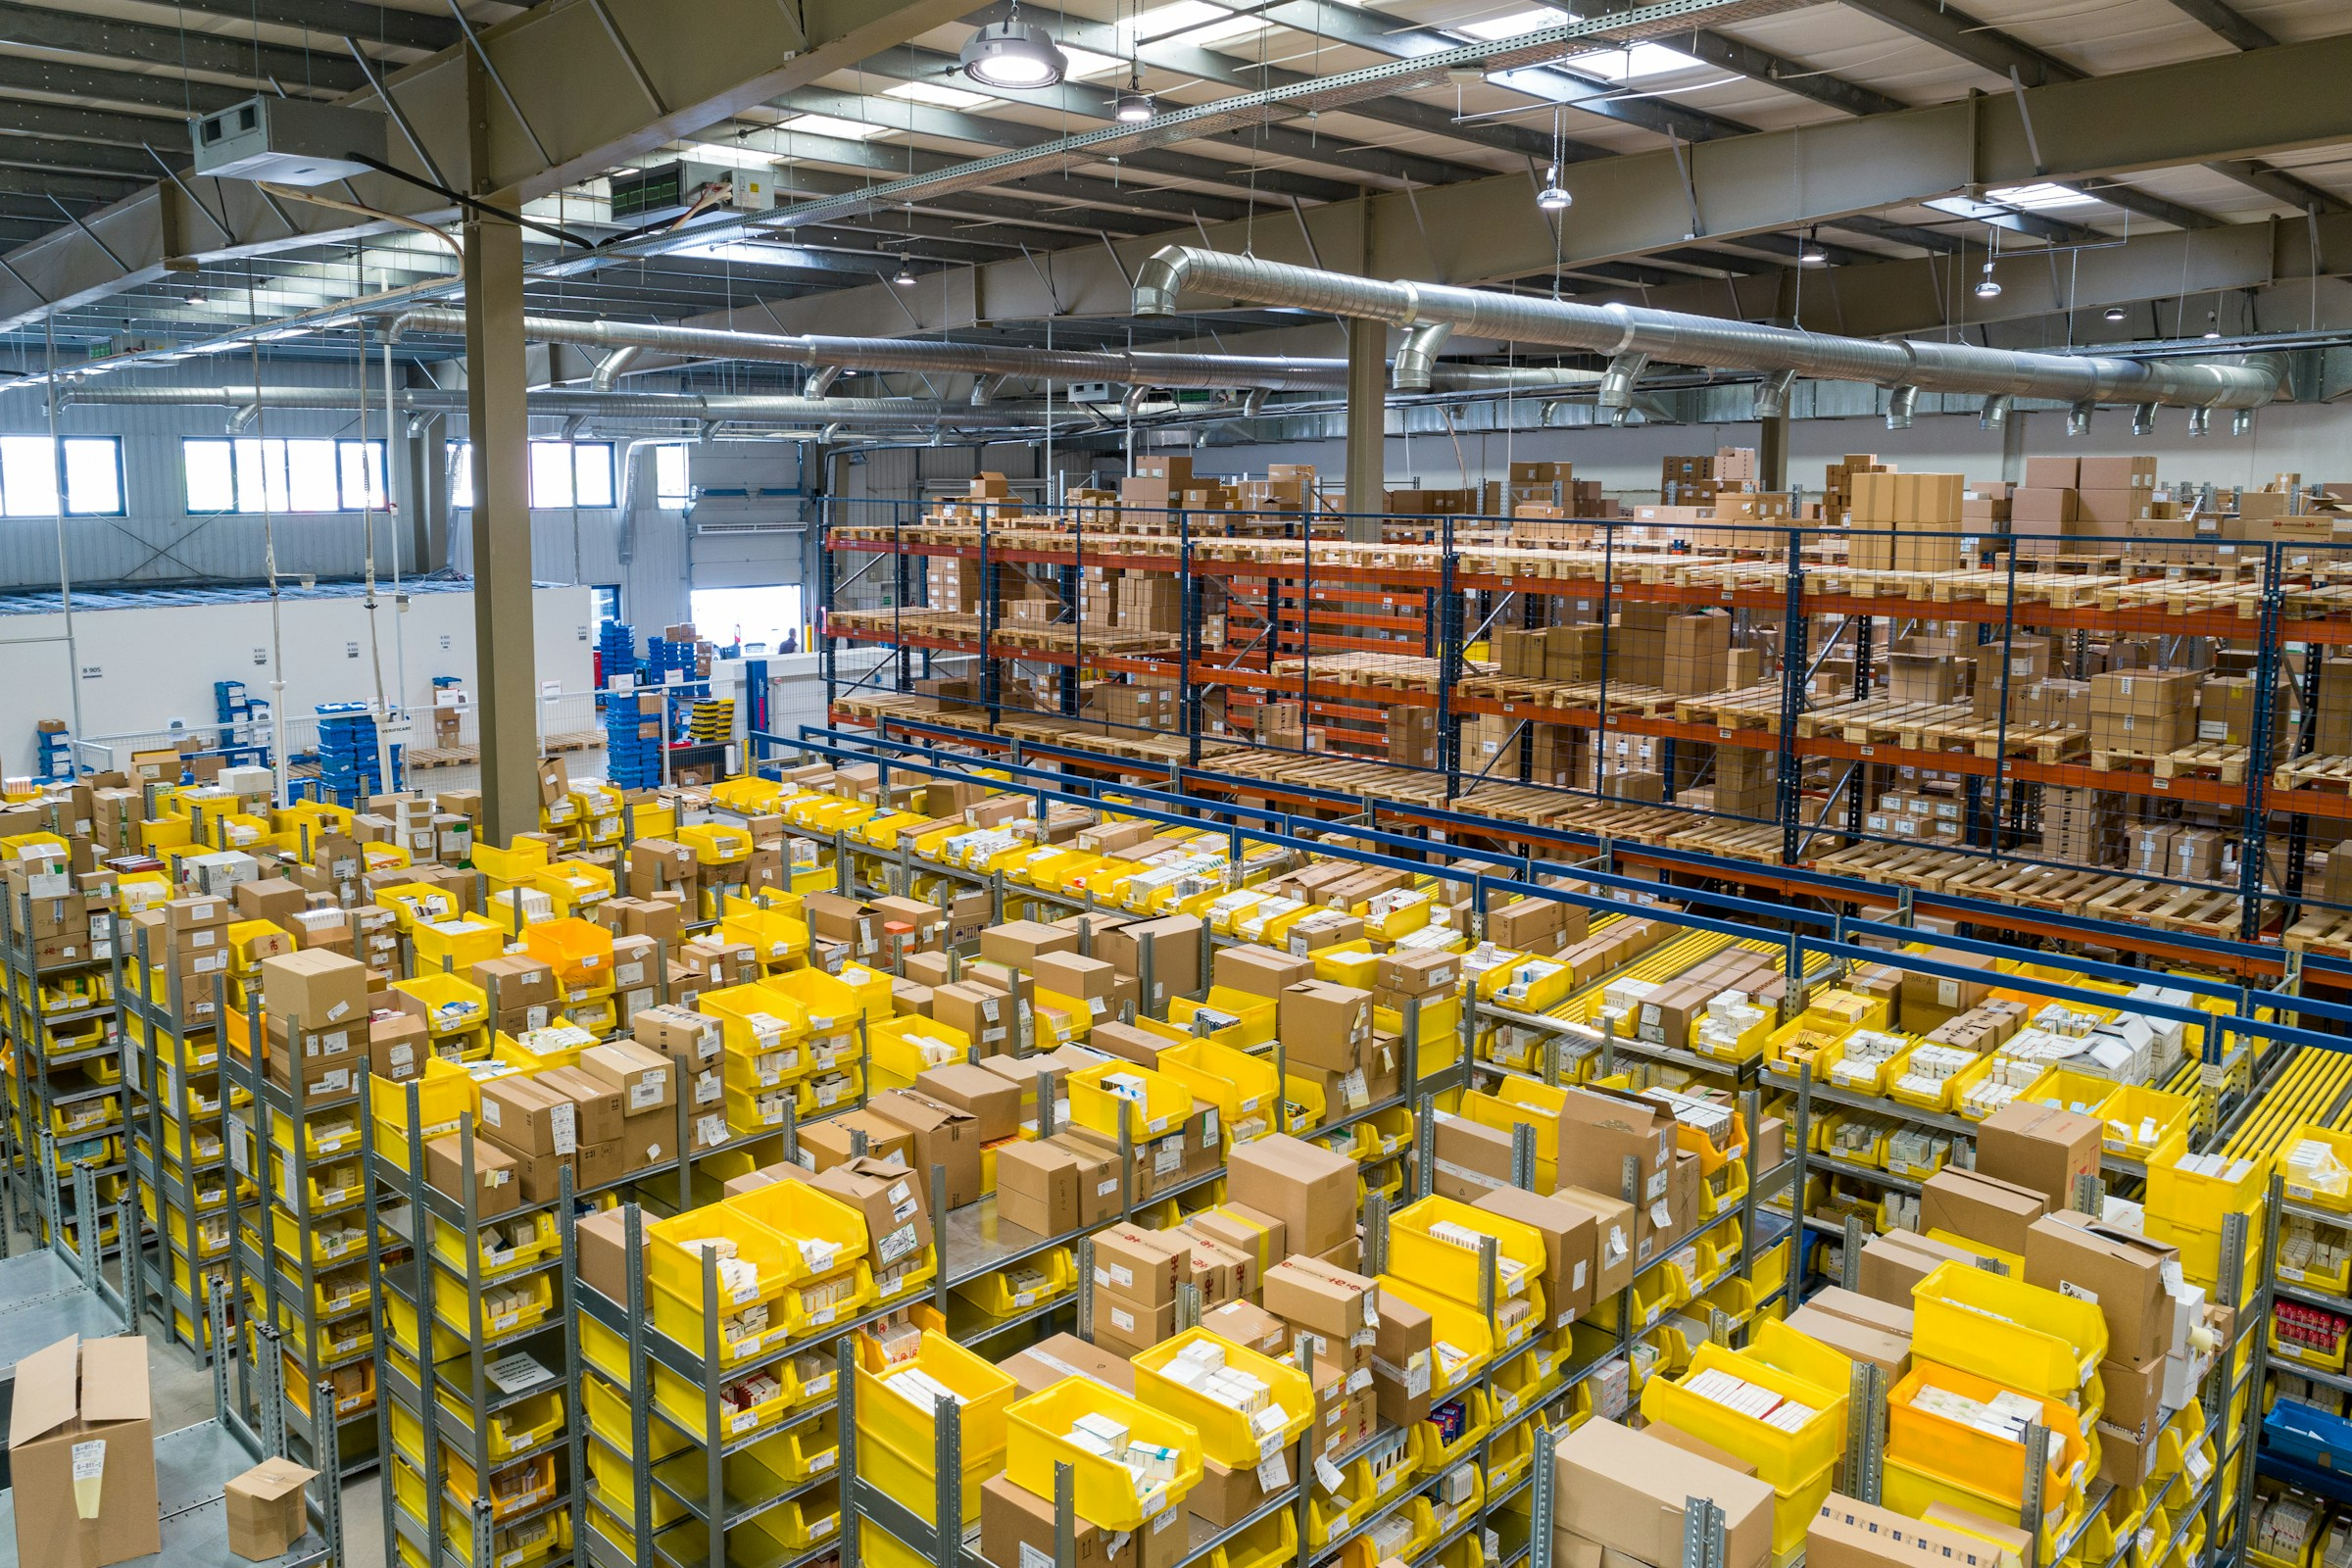
Warehouses and distribution centres accounted for 37% of the Q2 theft incidents cited by the company. The location of a theft can influence which party bears responsibility, especially when the cargo is waiting to be collected or has been handed to another carrier. Contract wording, custody records, seal checks, and the conditions of insurance determine how an incident moves from operational loss to a recoverable claim. Carrier vetting also needs to address impersonation and fraudulent collections, rather than relying only on an acceptable headline freight rate.
Late deliveries and incomplete consignments can create additional contractual costs. GEODIS gives an illustration in which a retailer applies a charge of 3% of goods value to non-compliant cases. At $100 million of goods with 10% of cases late or short, its example produces a $300,000 annual charge before corrective freight costs. That is an illustrative calculation dependent on the stated assumptions, not a typical penalty rate applied across the US retail sector. Individual retailers and supply contracts can use different formulas.
GEODIS identifies food and grocery, household and large-item delivery, high-technology goods, and personal care as categories with differing risk and service requirements. Large items may demand specialised equipment or additional labour; high-value technology can need tighter custody controls; and food shipments may require prescribed delivery windows or temperature conditions. Those requirements change the actual cost of a service and cannot be represented fully by a national index built from broad producer price series.
During a rate review, a shipper can compare the index with its own lane-level charges while separating basic transport prices from fuel, redelivery, waiting time, damage claims, and retailer penalties. A changed shipment mix or a deterioration in service can raise invoice totals without the same increase in underlying freight rates. The index provides an external comparison point, but the report contains no universal saving that can be attributed to a particular carrier-management measure.
Later GEODIS editions will show whether the 10.5% annual increase moderates and how the courier and local freight components develop. The company forecasts a Q4 composite above 145 as fuel and peak-season charges feed through, but that outcome has not yet been measured. Shippers’ actual exposure will continue to depend on the services purchased and the surcharge, claims, and performance conditions in their contracts.